September 25, 2026
Weekly Energy News
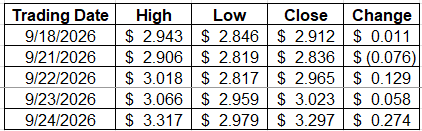
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
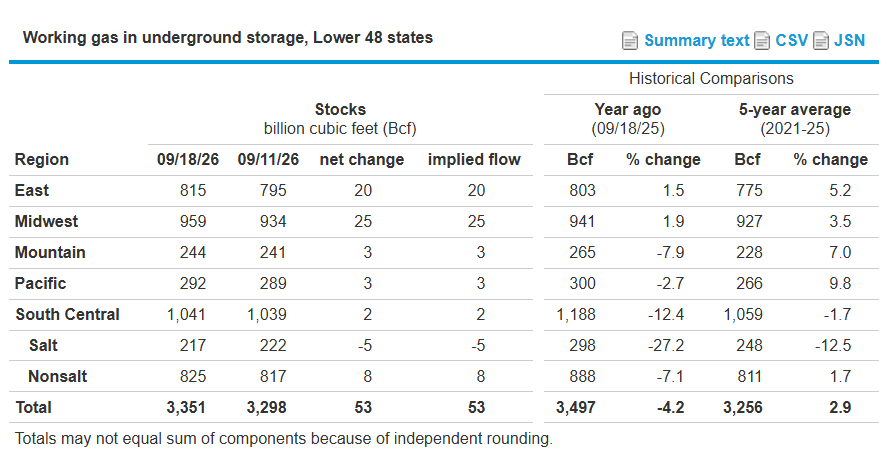
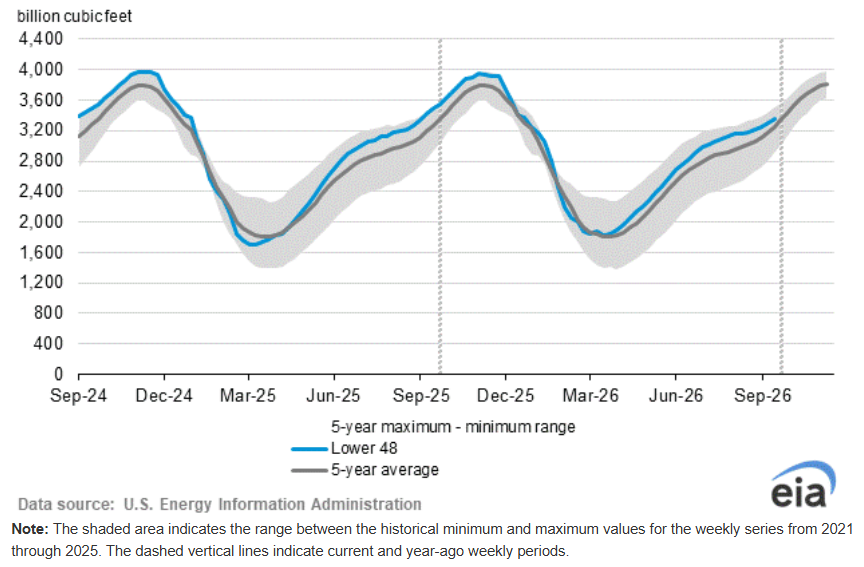
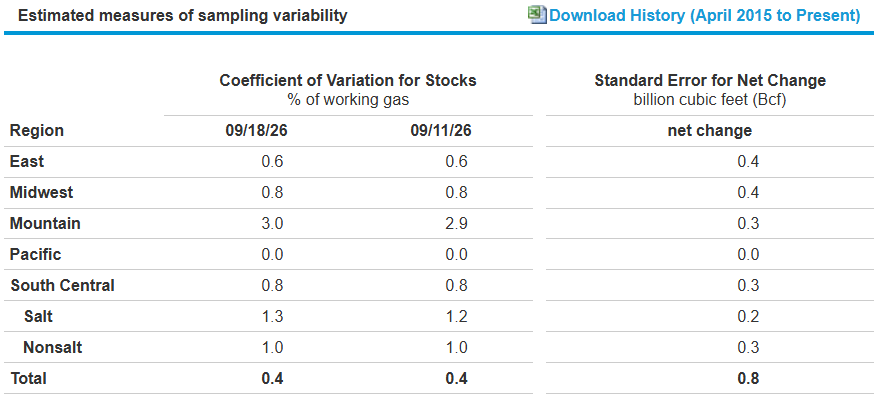
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
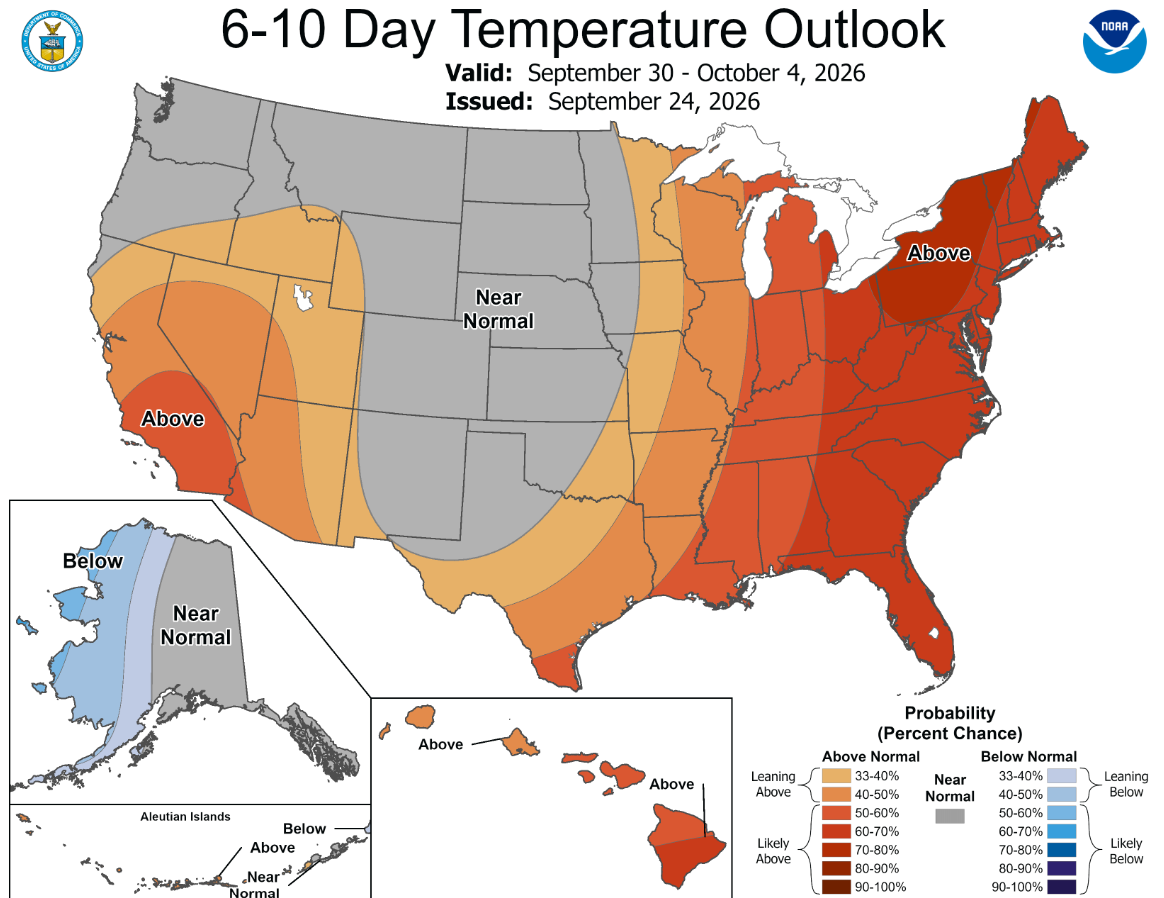
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
Market Data:
September 25, 2026
Weekly Energy News
September 25, 2026
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
Market Data:
September 25, 2026
September 25, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
September 25, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
September 25, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
September 25, 2026
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
September 25, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
September 25, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub October futures rallied 27 cents on September 24 to settle at $3.30/MMBtu, the first prompt-month close above $3 since July 10, after EIA data showed the storage surplus shrinking to its lowest level since April. The Platts national average cash price settled at $2.420/MMBtu for September 25 flows.
Cooler weather and Cove Point LNG maintenance loosened the market by about 800 MMcf/d this week, but the longer-term outlook remains supportive, with the DOE calling natural gas the most important fuel for meeting rising power demand from AI and manufacturing.
Storage Report: The EIA reported a 53 Bcf injection for the week ended September 18, in line with expectations but well below the five-year average. Total working gas stands at 3.351 Tcf, 2.9% above the five-year average, the smallest surplus since April, and 4.2% below year-ago levels. Another below-average build of about 57 Bcf is projected for the week ending September 25.
Weather: NOAA’s 6–10 day outlook (valid September 30–October 4) shows above-normal temperatures from the Mississippi Valley to the East Coast and across the Southwest, with near-normal readings in the Northwest and Plains. The warmth is mild compared to summer, so demand support should be modest heading into shoulder season.
Make Your Choice Gas Selection in Three Easy Steps
Click here to access our online tool, or call our Choice gas commodity experts at 1 (877) 790-4990.
Step 1: Enter your account number
- Your Black Hills Energy account number is located at the top right-hand corner of your bill.
Step 2: Review price options and make your selection
Step 3: Confirm your selection and enter your control number
- You received a control number in your 2026 Choice Gas selection packet mailed to you from Black Hills Energy. If you cannot locate this, you can retrieve your control number by calling 877-245-3506 or visit choicegas.com
Once enrolled, you will be removed from supplier marketing communications within 24 hours.


Sign Up for Our Energy Newsletters
Sign UpRecent Posts