October 23, 2026
Weekly Energy News
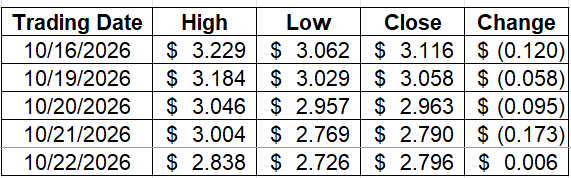
Market Update: NYMEX Henry Hub November futures settled at $2.796/MMBtu on October 22, up just 0.6 cents on the day but 44 cents lower week over week, after sliding to an eight-week low for the prompt month. Forecasts for mild weather into early November and rebounding production weighed on the market, and winter contracts fell to four-to-five-year lows, with December settling at $3.156/MMBtu and January at $3.563/MMBtu. Henry Hub cash settled at $2.950/MMBtu and the Platts national average at $2.330/MMBtu for October 23 flows.
Supply is recovering: U.S. production rebounded to an average of 111.3 Bcf/d this week as Appalachian output came back following pipeline maintenance, and S&P Global Energy CERA projects output could reach around 113 Bcf/d this winter. On the demand side, LNG feedgas climbed to a weekly record of 21 Bcf/d on strong Golden Pass and Plaquemines volumes, and QatarEnergy signed agreements to buy 4 million mt/year of LNG from Cheniere through 2054. In Washington, Senate staffers touted a sweeping bipartisan permitting reform package, though several states have raised concerns about its Clean Water Act provisions.
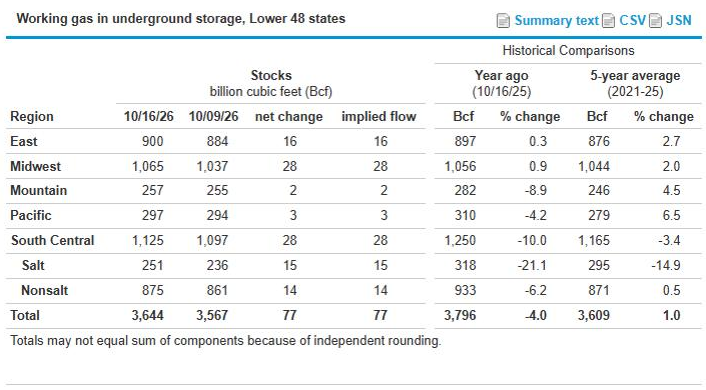
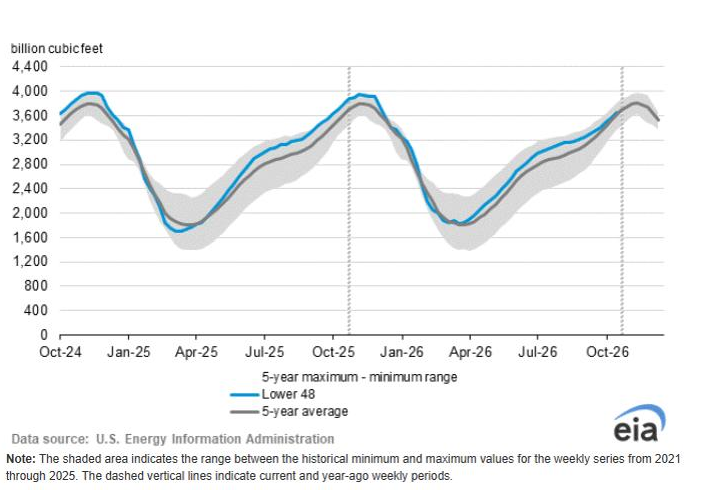
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 16, matching the 77 Bcf consensus but below the five-year average of 87 Bcf. Total working gas stands at 3.644 Tcf, 35 Bcf (1.0%) above the five-year average, the tenth straight week the surplus has narrowed, and 152 Bcf (4.0%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 28–November 1) favors above-normal temperatures across most of the U.S. east of the Rockies, with the highest odds centered on the Tennessee Valley and Mid-South, while below-normal readings are favored in the Pacific Northwest. Continued mild weather should keep heating demand in check and allow injections to continue into mid-November.

Market Data:
October 23, 2026
Weekly Energy News
October 23, 2026
Market Update: NYMEX Henry Hub November futures settled at $2.796/MMBtu on October 22, up just 0.6 cents on the day but 44 cents lower week over week, after sliding to an eight-week low for the prompt month. Forecasts for mild weather into early November and rebounding production weighed on the market, and winter contracts fell to four-to-five-year lows, with December settling at $3.156/MMBtu and January at $3.563/MMBtu. Henry Hub cash settled at $2.950/MMBtu and the Platts national average at $2.330/MMBtu for October 23 flows.
Supply is recovering: U.S. production rebounded to an average of 111.3 Bcf/d this week as Appalachian output came back following pipeline maintenance, and S&P Global Energy CERA projects output could reach around 113 Bcf/d this winter. On the demand side, LNG feedgas climbed to a weekly record of 21 Bcf/d on strong Golden Pass and Plaquemines volumes, and QatarEnergy signed agreements to buy 4 million mt/year of LNG from Cheniere through 2054. In Washington, Senate staffers touted a sweeping bipartisan permitting reform package, though several states have raised concerns about its Clean Water Act provisions.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 16, matching the 77 Bcf consensus but below the five-year average of 87 Bcf. Total working gas stands at 3.644 Tcf, 35 Bcf (1.0%) above the five-year average, the tenth straight week the surplus has narrowed, and 152 Bcf (4.0%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 28–November 1) favors above-normal temperatures across most of the U.S. east of the Rockies, with the highest odds centered on the Tennessee Valley and Mid-South, while below-normal readings are favored in the Pacific Northwest. Continued mild weather should keep heating demand in check and allow injections to continue into mid-November.
Market Data:
October 23, 2026
October 23, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub November futures settled at $2.796/MMBtu on October 22, up just 0.6 cents on the day but 44 cents lower week over week, after sliding to an eight-week low for the prompt month. Forecasts for mild weather into early November and rebounding production weighed on the market, and winter contracts fell to four-to-five-year lows, with December settling at $3.156/MMBtu and January at $3.563/MMBtu. Henry Hub cash settled at $2.950/MMBtu and the Platts national average at $2.330/MMBtu for October 23 flows.
Supply is recovering: U.S. production rebounded to an average of 111.3 Bcf/d this week as Appalachian output came back following pipeline maintenance, and S&P Global Energy CERA projects output could reach around 113 Bcf/d this winter. On the demand side, LNG feedgas climbed to a weekly record of 21 Bcf/d on strong Golden Pass and Plaquemines volumes, and QatarEnergy signed agreements to buy 4 million mt/year of LNG from Cheniere through 2054. In Washington, Senate staffers touted a sweeping bipartisan permitting reform package, though several states have raised concerns about its Clean Water Act provisions.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 16, matching the 77 Bcf consensus but below the five-year average of 87 Bcf. Total working gas stands at 3.644 Tcf, 35 Bcf (1.0%) above the five-year average, the tenth straight week the surplus has narrowed, and 152 Bcf (4.0%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 28–November 1) favors above-normal temperatures across most of the U.S. east of the Rockies, with the highest odds centered on the Tennessee Valley and Mid-South, while below-normal readings are favored in the Pacific Northwest. Continued mild weather should keep heating demand in check and allow injections to continue into mid-November.
October 23, 2026
Market Update: NYMEX Henry Hub November futures settled at $2.796/MMBtu on October 22, up just 0.6 cents on the day but 44 cents lower week over week, after sliding to an eight-week low for the prompt month. Forecasts for mild weather into early November and rebounding production weighed on the market, and winter contracts fell to four-to-five-year lows, with December settling at $3.156/MMBtu and January at $3.563/MMBtu. Henry Hub cash settled at $2.950/MMBtu and the Platts national average at $2.330/MMBtu for October 23 flows.
Supply is recovering: U.S. production rebounded to an average of 111.3 Bcf/d this week as Appalachian output came back following pipeline maintenance, and S&P Global Energy CERA projects output could reach around 113 Bcf/d this winter. On the demand side, LNG feedgas climbed to a weekly record of 21 Bcf/d on strong Golden Pass and Plaquemines volumes, and QatarEnergy signed agreements to buy 4 million mt/year of LNG from Cheniere through 2054. In Washington, Senate staffers touted a sweeping bipartisan permitting reform package, though several states have raised concerns about its Clean Water Act provisions.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 16, matching the 77 Bcf consensus but below the five-year average of 87 Bcf. Total working gas stands at 3.644 Tcf, 35 Bcf (1.0%) above the five-year average, the tenth straight week the surplus has narrowed, and 152 Bcf (4.0%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 28–November 1) favors above-normal temperatures across most of the U.S. east of the Rockies, with the highest odds centered on the Tennessee Valley and Mid-South, while below-normal readings are favored in the Pacific Northwest. Continued mild weather should keep heating demand in check and allow injections to continue into mid-November.
October 23, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub November futures settled at $2.796/MMBtu on October 22, up just 0.6 cents on the day but 44 cents lower week over week, after sliding to an eight-week low for the prompt month. Forecasts for mild weather into early November and rebounding production weighed on the market, and winter contracts fell to four-to-five-year lows, with December settling at $3.156/MMBtu and January at $3.563/MMBtu. Henry Hub cash settled at $2.950/MMBtu and the Platts national average at $2.330/MMBtu for October 23 flows.
Supply is recovering: U.S. production rebounded to an average of 111.3 Bcf/d this week as Appalachian output came back following pipeline maintenance, and S&P Global Energy CERA projects output could reach around 113 Bcf/d this winter. On the demand side, LNG feedgas climbed to a weekly record of 21 Bcf/d on strong Golden Pass and Plaquemines volumes, and QatarEnergy signed agreements to buy 4 million mt/year of LNG from Cheniere through 2054. In Washington, Senate staffers touted a sweeping bipartisan permitting reform package, though several states have raised concerns about its Clean Water Act provisions.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 16, matching the 77 Bcf consensus but below the five-year average of 87 Bcf. Total working gas stands at 3.644 Tcf, 35 Bcf (1.0%) above the five-year average, the tenth straight week the surplus has narrowed, and 152 Bcf (4.0%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 28–November 1) favors above-normal temperatures across most of the U.S. east of the Rockies, with the highest odds centered on the Tennessee Valley and Mid-South, while below-normal readings are favored in the Pacific Northwest. Continued mild weather should keep heating demand in check and allow injections to continue into mid-November.
Make Your Choice Gas Selection in Three Easy Steps
Click here to access our online tool, or call our Choice gas commodity experts at 1 (877) 790-4990.
Step 1: Enter your account number
- Your Black Hills Energy account number is located at the top right-hand corner of your bill.
Step 2: Review price options and make your selection
Step 3: Confirm your selection and enter your control number
- You received a control number in your 2026 Choice Gas selection packet mailed to you from Black Hills Energy. If you cannot locate this, you can retrieve your control number by calling 877-245-3506 or visit choicegas.com
Once enrolled, you will be removed from supplier marketing communications within 24 hours.


Sign Up for Our Energy Newsletters
Sign UpRecent Posts