October 2, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub November futures, now the prompt contract, fell 5.9 cents on October 1 to settle at $2.967/MMBtu, giving back much of last week’s rally above $3 even as the weekly storage build came in well below the five-year average. October bidweek settled at $3.00/MMBtu at Henry Hub, up 10 cents from September, while the Platts national average cash price settled at $2.470/MMBtu for October 2 flows.
Mild fall weather and lighter power demand are loosening the market, with Lower 48 demand down about 1.6 Bcf/d week over week. Planned maintenance at Cove Point LNG has also pushed roughly 800 MMcf/d of gas back into the Northeast, driving Appalachian and Northeast cash prices to multiyear lows. Longer term, LNG export growth remains supportive, as Venture Global signed a 20-year supply deal with ConocoPhillips and South Korea agreed to begin reviews of the Alaska LNG project.
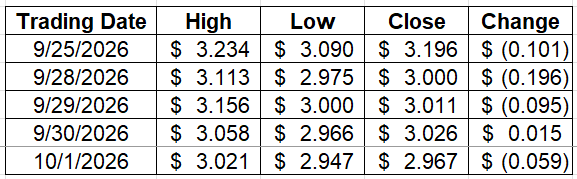
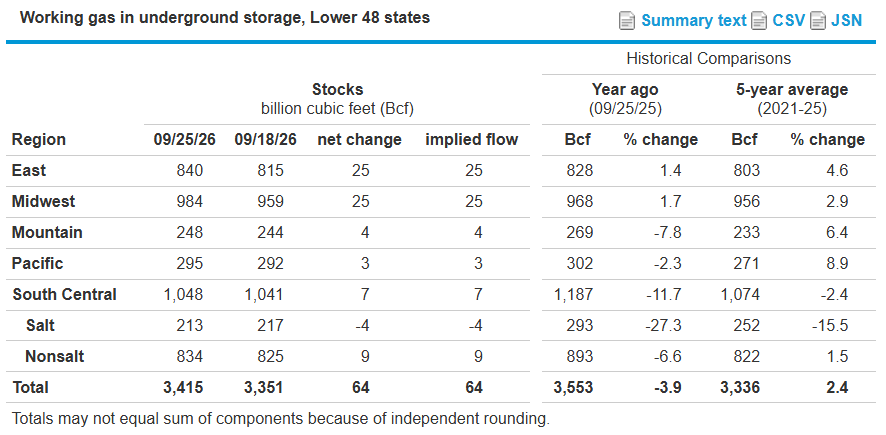
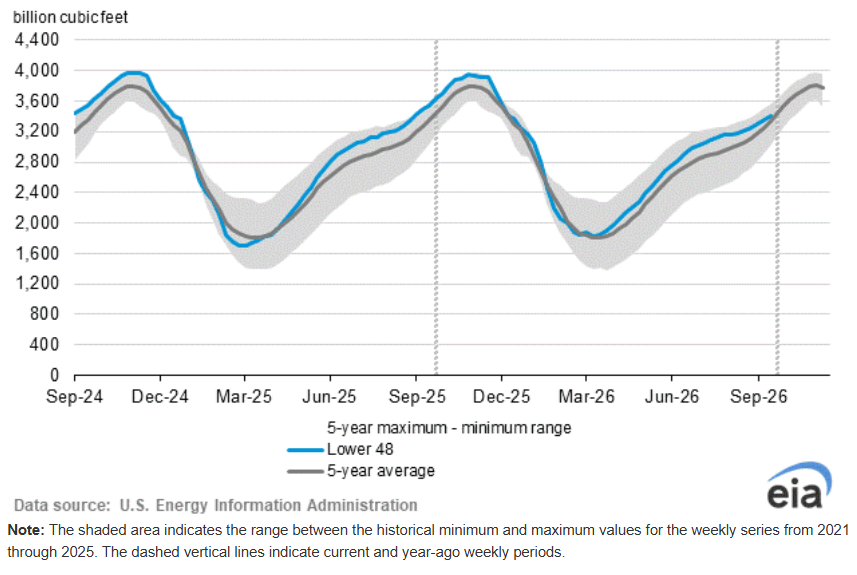
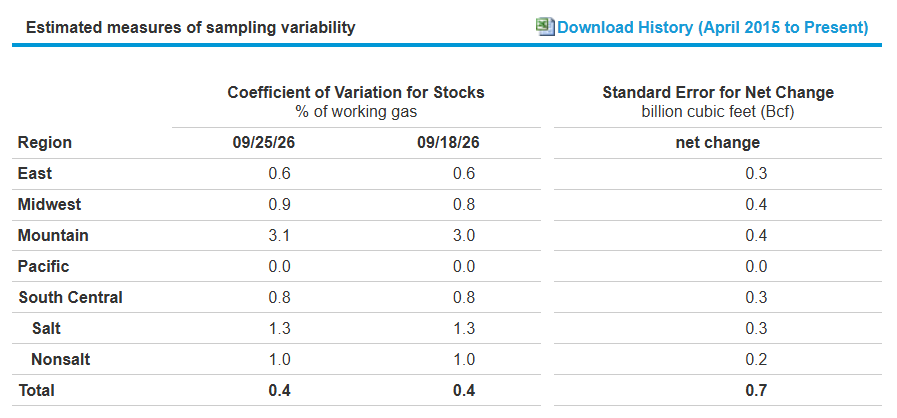
Storage Report: The EIA reported a 64 Bcf injection for the week ended September 25, slightly above the 62 Bcf consensus but well below the five-year average of 80 Bcf. Total working gas stands at 3.415 Tcf, 79 Bcf (2.4%) above the five-year average, and 138 Bcf (3.9%) below year-ago levels.
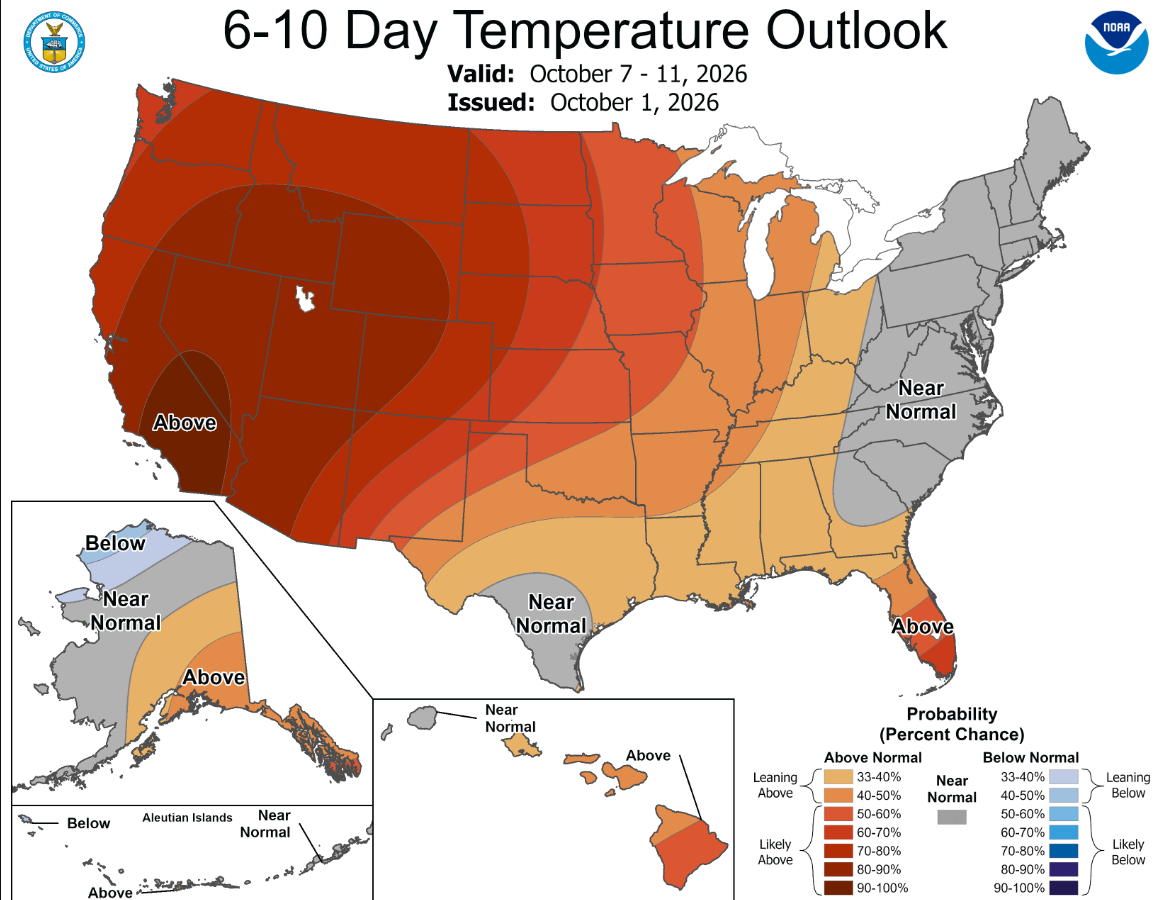
Weather: NOAA’s 6–10 day outlook (valid October 7–11) favors above-normal temperatures across most of the West and central U.S., with near-normal readings along parts of the East Coast. Warm, mild weather in early October should keep heating demand light and support continued strong storage injections.
Market Data:
October 2, 2026
Weekly Energy News
October 2, 2026
Market Update: NYMEX Henry Hub November futures, now the prompt contract, fell 5.9 cents on October 1 to settle at $2.967/MMBtu, giving back much of last week’s rally above $3 even as the weekly storage build came in well below the five-year average. October bidweek settled at $3.00/MMBtu at Henry Hub, up 10 cents from September, while the Platts national average cash price settled at $2.470/MMBtu for October 2 flows.
Mild fall weather and lighter power demand are loosening the market, with Lower 48 demand down about 1.6 Bcf/d week over week. Planned maintenance at Cove Point LNG has also pushed roughly 800 MMcf/d of gas back into the Northeast, driving Appalachian and Northeast cash prices to multiyear lows. Longer term, LNG export growth remains supportive, as Venture Global signed a 20-year supply deal with ConocoPhillips and South Korea agreed to begin reviews of the Alaska LNG project.
Storage Report: The EIA reported a 64 Bcf injection for the week ended September 25, slightly above the 62 Bcf consensus but well below the five-year average of 80 Bcf. Total working gas stands at 3.415 Tcf, 79 Bcf (2.4%) above the five-year average, and 138 Bcf (3.9%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 7–11) favors above-normal temperatures across most of the West and central U.S., with near-normal readings along parts of the East Coast. Warm, mild weather in early October should keep heating demand light and support continued strong storage injections.
Market Data:
October 2, 2026
October 2, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub November futures, now the prompt contract, fell 5.9 cents on October 1 to settle at $2.967/MMBtu, giving back much of last week’s rally above $3 even as the weekly storage build came in well below the five-year average. October bidweek settled at $3.00/MMBtu at Henry Hub, up 10 cents from September, while the Platts national average cash price settled at $2.470/MMBtu for October 2 flows.
Mild fall weather and lighter power demand are loosening the market, with Lower 48 demand down about 1.6 Bcf/d week over week. Planned maintenance at Cove Point LNG has also pushed roughly 800 MMcf/d of gas back into the Northeast, driving Appalachian and Northeast cash prices to multiyear lows. Longer term, LNG export growth remains supportive, as Venture Global signed a 20-year supply deal with ConocoPhillips and South Korea agreed to begin reviews of the Alaska LNG project.
Storage Report: The EIA reported a 64 Bcf injection for the week ended September 25, slightly above the 62 Bcf consensus but well below the five-year average of 80 Bcf. Total working gas stands at 3.415 Tcf, 79 Bcf (2.4%) above the five-year average, and 138 Bcf (3.9%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 7–11) favors above-normal temperatures across most of the West and central U.S., with near-normal readings along parts of the East Coast. Warm, mild weather in early October should keep heating demand light and support continued strong storage injections.
October 2, 2026
Market Update: NYMEX Henry Hub November futures, now the prompt contract, fell 5.9 cents on October 1 to settle at $2.967/MMBtu, giving back much of last week’s rally above $3 even as the weekly storage build came in well below the five-year average. October bidweek settled at $3.00/MMBtu at Henry Hub, up 10 cents from September, while the Platts national average cash price settled at $2.470/MMBtu for October 2 flows.
Mild fall weather and lighter power demand are loosening the market, with Lower 48 demand down about 1.6 Bcf/d week over week. Planned maintenance at Cove Point LNG has also pushed roughly 800 MMcf/d of gas back into the Northeast, driving Appalachian and Northeast cash prices to multiyear lows. Longer term, LNG export growth remains supportive, as Venture Global signed a 20-year supply deal with ConocoPhillips and South Korea agreed to begin reviews of the Alaska LNG project.
Storage Report: The EIA reported a 64 Bcf injection for the week ended September 25, slightly above the 62 Bcf consensus but well below the five-year average of 80 Bcf. Total working gas stands at 3.415 Tcf, 79 Bcf (2.4%) above the five-year average, and 138 Bcf (3.9%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 7–11) favors above-normal temperatures across most of the West and central U.S., with near-normal readings along parts of the East Coast. Warm, mild weather in early October should keep heating demand light and support continued strong storage injections.
October 2, 2026
Weekly Energy News
Market Update: NYMEX Henry Hub November futures, now the prompt contract, fell 5.9 cents on October 1 to settle at $2.967/MMBtu, giving back much of last week’s rally above $3 even as the weekly storage build came in well below the five-year average. October bidweek settled at $3.00/MMBtu at Henry Hub, up 10 cents from September, while the Platts national average cash price settled at $2.470/MMBtu for October 2 flows.
Mild fall weather and lighter power demand are loosening the market, with Lower 48 demand down about 1.6 Bcf/d week over week. Planned maintenance at Cove Point LNG has also pushed roughly 800 MMcf/d of gas back into the Northeast, driving Appalachian and Northeast cash prices to multiyear lows. Longer term, LNG export growth remains supportive, as Venture Global signed a 20-year supply deal with ConocoPhillips and South Korea agreed to begin reviews of the Alaska LNG project.
Storage Report: The EIA reported a 64 Bcf injection for the week ended September 25, slightly above the 62 Bcf consensus but well below the five-year average of 80 Bcf. Total working gas stands at 3.415 Tcf, 79 Bcf (2.4%) above the five-year average, and 138 Bcf (3.9%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid October 7–11) favors above-normal temperatures across most of the West and central U.S., with near-normal readings along parts of the East Coast. Warm, mild weather in early October should keep heating demand light and support continued strong storage injections.
Make Your Choice Gas Selection in Three Easy Steps
Click here to access our online tool, or call our Choice gas commodity experts at 1 (877) 790-4990.
Step 1: Enter your account number
- Your Black Hills Energy account number is located at the top right-hand corner of your bill.
Step 2: Review price options and make your selection
Step 3: Confirm your selection and enter your control number
- You received a control number in your 2026 Choice Gas selection packet mailed to you from Black Hills Energy. If you cannot locate this, you can retrieve your control number by calling 877-245-3506 or visit choicegas.com
Once enrolled, you will be removed from supplier marketing communications within 24 hours.


Sign Up for Our Energy Newsletters
Sign UpRecent Posts