November 6, 2026
Weekly Energy News
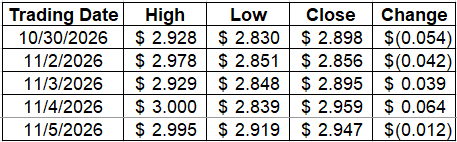
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
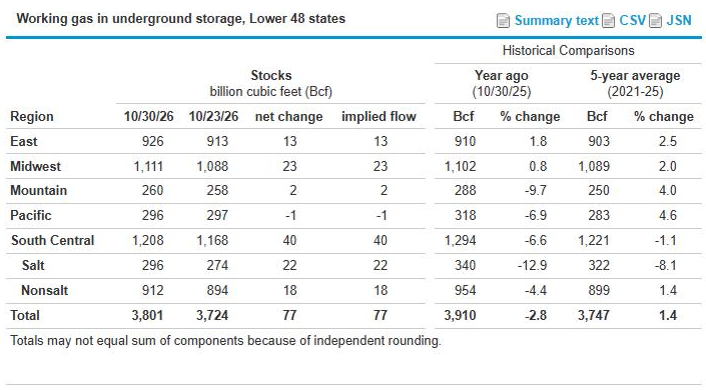
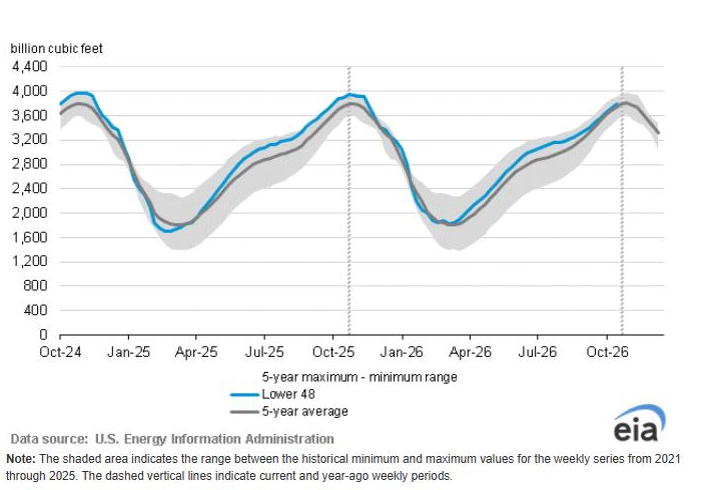
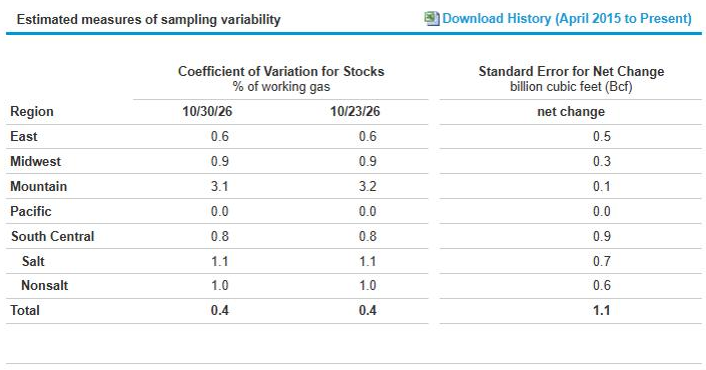
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.

Market Data:
November 6, 2026
Weekly Energy News
November 6, 2026
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.
Market Data:
November 6, 2026
November 6, 2026
Weekly Energy News
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.
November 6, 2026
Weekly Energy News
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.
November 6, 2026
Weekly Energy News
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.
November 6, 2026
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.
November 6, 2026
Weekly Energy News
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.
November 6, 2026
Weekly Energy News
Market Update: Natural gas prices held steady this week as mild weather offset the start of the heating season. NYMEX Henry Hub December futures settled at $2.947/MMBtu on November 5, down about 1 cent on the day and essentially flat from a week earlier, after trading mostly between the mid-$2.80s and upper-$2.90s over the past two weeks. The prompt contract briefly tested resistance near $3/MMBtu following Thursday's storage report before settling lower. Further out the curve, January settled at $3.413/MMBtu, about 47 cents above December, while March settled at $2.399/MMBtu. Henry Hub cash edged up 1.5 cents to $2.625/MMBtu for November 6 flows.
Weather and supply remain the key headwinds. Forecasts call for very mild weather into Thanksgiving, with the most pronounced warmth across the Upper Midwest and Northeast, and continued record warmth could erode the winter risk premium built into NYMEX prices. Supply growth is also steady: Targa Resources reported record third-quarter Permian volumes of 7.5 Bcf/d, up 14% from a year ago, and Kinetik pointed to roughly 13 Bcf/d of new Permian pipeline capacity expected to come online over the next several years.
Storage Report: The EIA reported a 77 Bcf injection for the week ended October 30, slightly below the 79 Bcf Platts survey estimate but well above the five-year average of 61 Bcf and last year's 39 Bcf. Total working gas stands at 3.801 Tcf, 54 Bcf (1.4%) above the five-year average and 109 Bcf (2.8%) below year-ago levels.
Weather: NOAA’s 6–10 day outlook (valid November 11–15) favors above-normal temperatures across the western two-thirds of the country, with the highest odds over the northern Rockies and northern Plains, while near-normal temperatures are favored across the East and Southeast and parts of New England lean below normal. The mild pattern across much of the country should keep heating demand in check in the near term.
Make Your Choice Gas Selection in Three Easy Steps
Click here to access our online tool, or call our Choice gas commodity experts at 1 (877) 790-4990.
Step 1: Enter your account number
- Your Black Hills Energy account number is located at the top right-hand corner of your bill.
Step 2: Review price options and make your selection
Step 3: Confirm your selection and enter your control number
- You received a control number in your 2026 Choice Gas selection packet mailed to you from Black Hills Energy. If you cannot locate this, you can retrieve your control number by calling 877-245-3506 or visit choicegas.com
Once enrolled, you will be removed from supplier marketing communications within 24 hours.


Sign Up for Our Energy Newsletters
Sign UpRecent Posts