November 20, 2026
Weekly Energy News
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
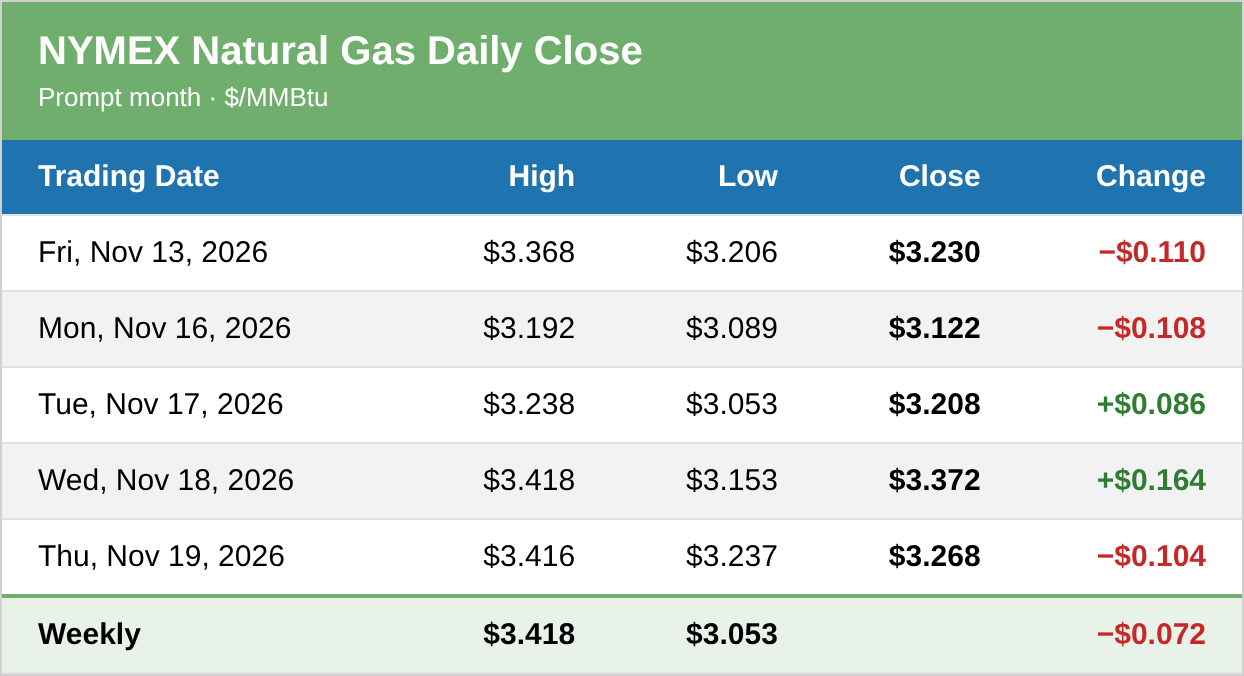
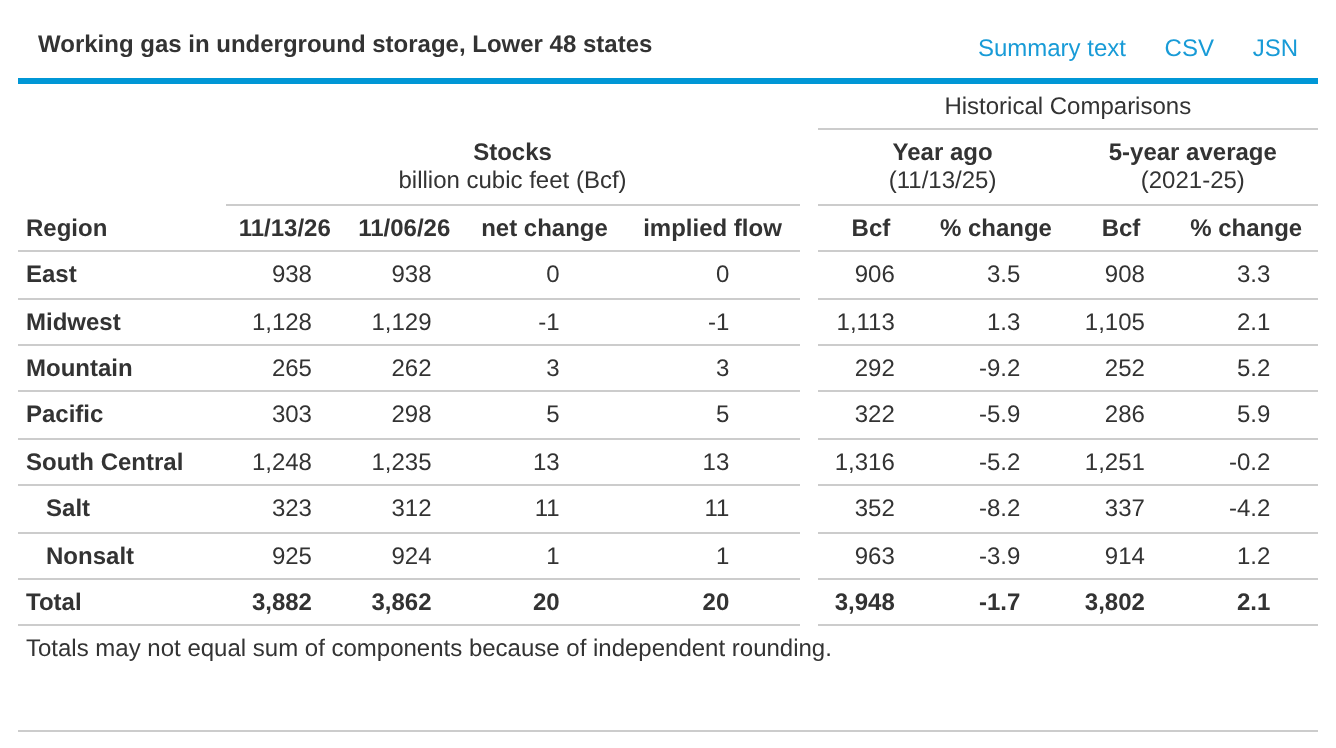
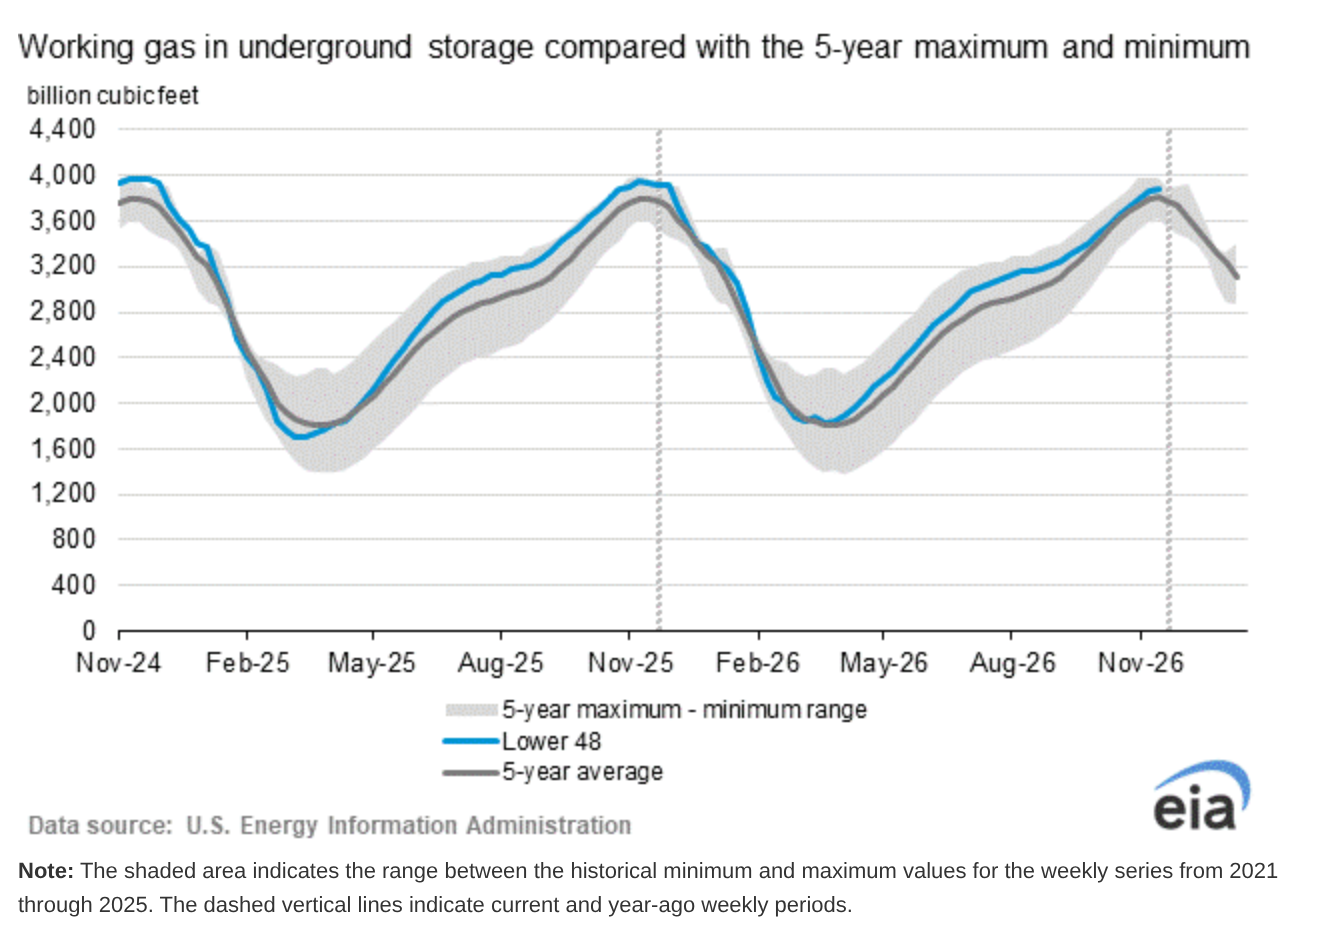
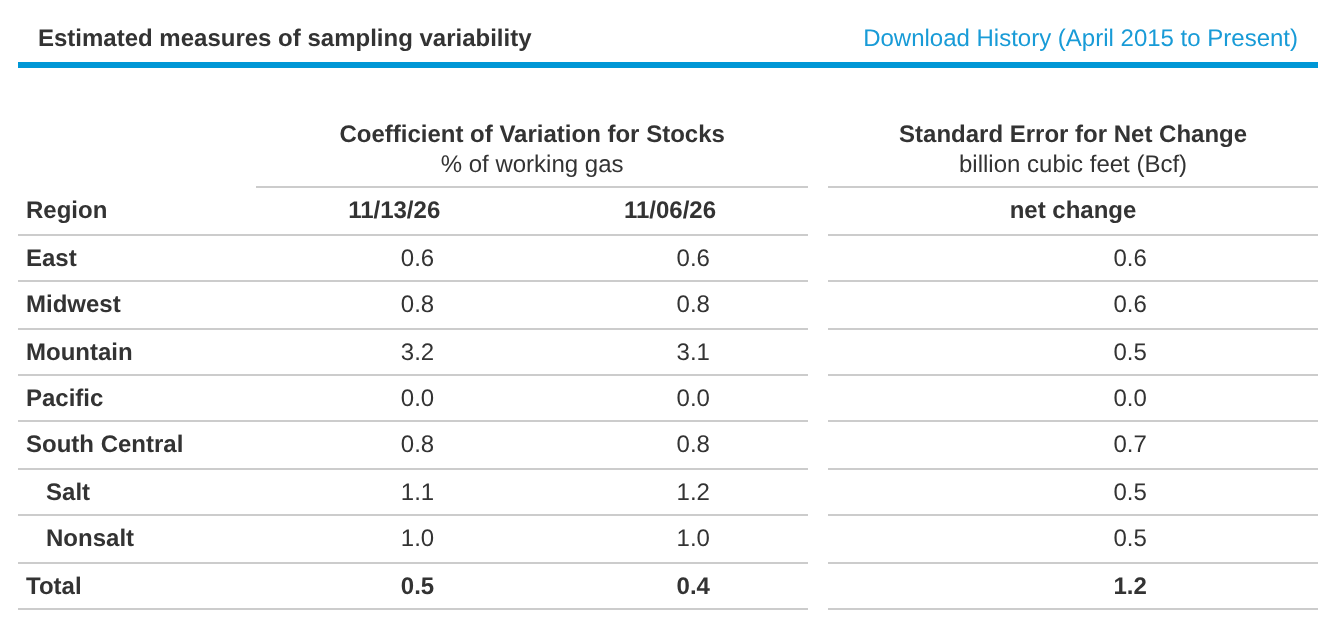
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.

Market Data:
November 20, 2026
Weekly Energy News
November 20, 2026
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.
Market Data:
November 20, 2026
November 20, 2026
Weekly Energy News
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.
November 20, 2026
Weekly Energy News
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.
November 20, 2026
Weekly Energy News
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.
November 20, 2026
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.
November 20, 2026
Weekly Energy News
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.
November 20, 2026
Weekly Energy News
Market Update: Natural gas futures swung this week as forecasts turned colder for the eastern U.S. NYMEX Henry Hub December futures settled at $3.268/MMBtu on November 19, down about 7 cents from a week earlier, after dipping to $3.122 on November 16 and rallying to $3.372 on November 18. January continues to carry a winter premium at $3.681. Spot prices were mixed: Henry Hub cash rose 6 cents to $3.315 for Friday flows, while the Platts national average slipped to $2.320 as Midwest, Midcontinent and Texas hubs eased.
Federal regulators were busy this week. On November 19, FERC approved Cheniere’s three-train expansion of the Sabine Pass LNG terminal in Louisiana, with a final investment decision on the first train targeted for early 2027, and authorized a batch of pipeline projects adding more than 5 million Dth/d of transportation capacity. In its winter outlook, FERC staff said U.S. gas production should average nearly 116 Bcf/d this winter, up 5% from last year, and that prices at most major hubs are expected to be lower than last winter, though New England and New York will likely remain elevated.
Storage Report: The EIA reported a 20 Bcf injection for the week ended November 13, well below the Platts survey estimate of 29 Bcf but above the five-year average build of 15 Bcf, as colder weather in the East and Midwest tightened the market. Total working gas stands at 3.882 Tcf, 80 Bcf (2.1%) above the five-year average and 66 Bcf (1.7%) below year-ago levels. Analysts expect storage to flip to withdrawals in next week’s report.
Weather: NOAA’s 6–10 day outlook (valid November 25–29) favors below-normal temperatures across Texas, the Gulf Coast and the lower Mississippi Valley, with above-normal temperatures across the West, northern Plains and upper Great Lakes and near-normal conditions for much of the East. The mixed pattern points to moderate heating demand over the Thanksgiving holiday week.
Make Your Choice Gas Selection in Three Easy Steps
Click here to access our online tool, or call our Choice gas commodity experts at 1 (877) 790-4990.
Step 1: Enter your account number
- Your Black Hills Energy account number is located at the top right-hand corner of your bill.
Step 2: Review price options and make your selection
Step 3: Confirm your selection and enter your control number
- You received a control number in your 2026 Choice Gas selection packet mailed to you from Black Hills Energy. If you cannot locate this, you can retrieve your control number by calling 877-245-3506 or visit choicegas.com
Once enrolled, you will be removed from supplier marketing communications within 24 hours.


Sign Up for Our Energy Newsletters
Sign UpRecent Posts