September 18, 2026
Weekly Energy News
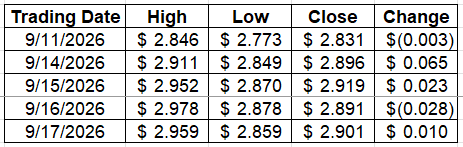
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
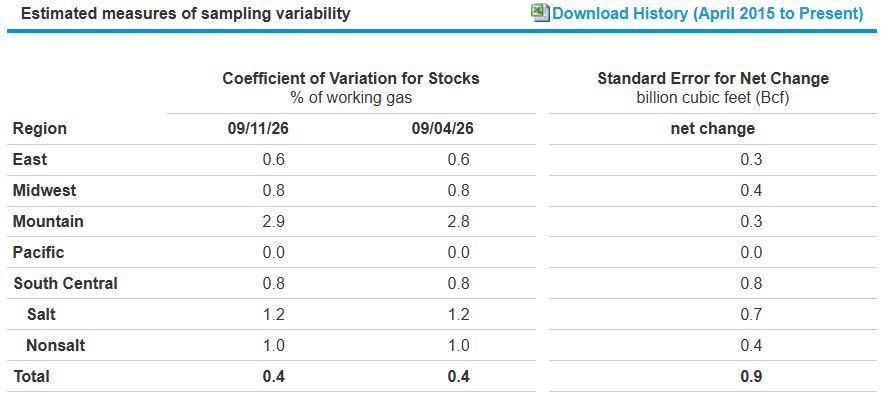
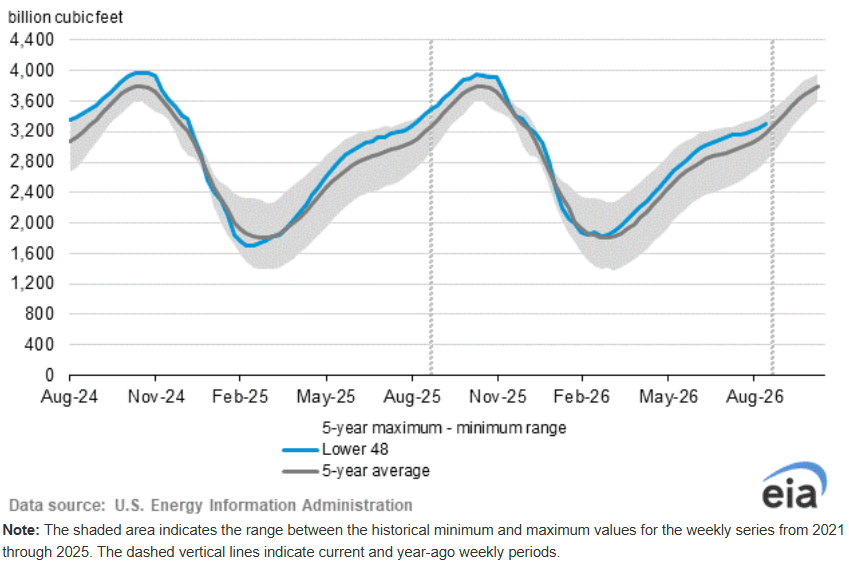
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
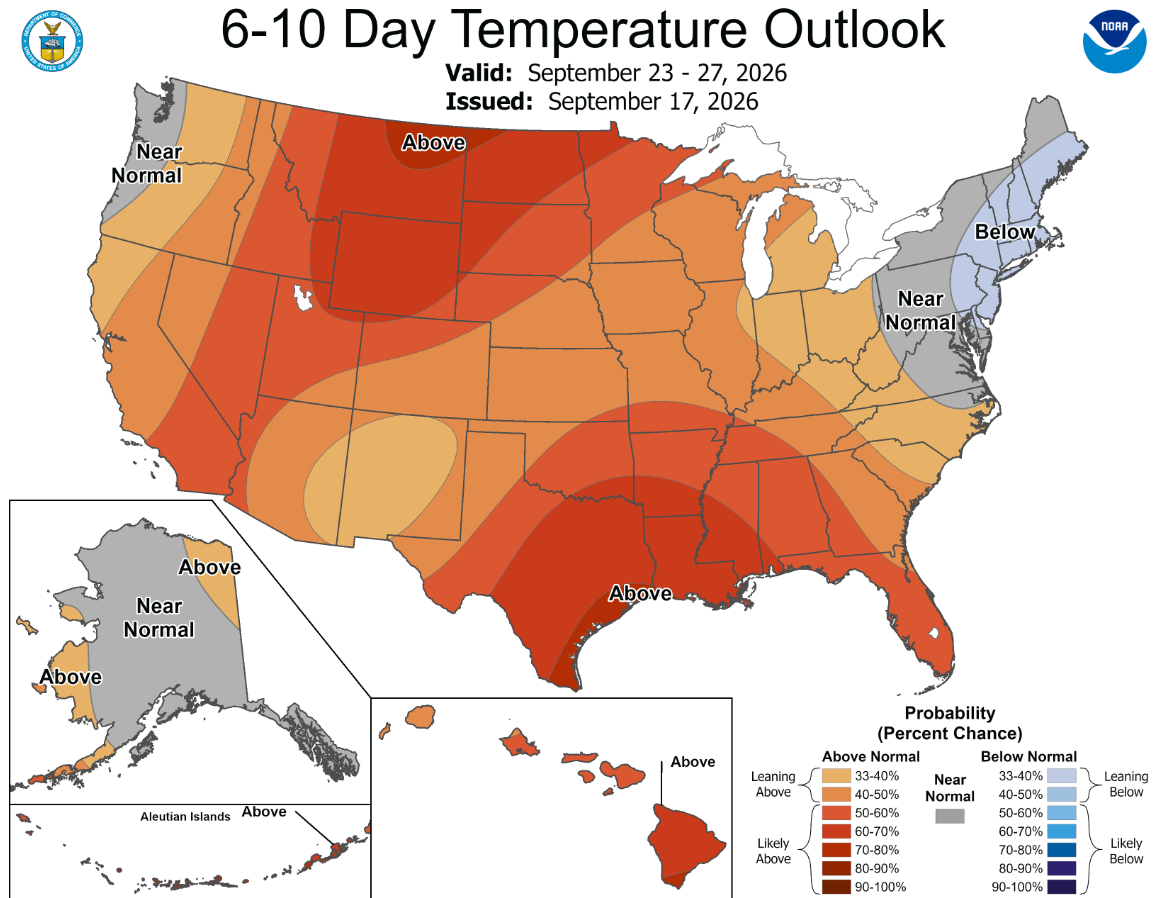
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
Market Data:
September 18, 2026
Weekly Energy News
September 18, 2026
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
Market Data:
September 18, 2026
September 18, 2026
Weekly Energy News
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
September 18, 2026
Weekly Energy News
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
September 18, 2026
Weekly Energy News
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
September 18, 2026
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
September 18, 2026
Weekly Energy News
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
September 18, 2026
Weekly Energy News
Market Update: Natural gas prices held near recent levels this week, with NYMEX Henry Hub October futures settling at $2.901/MMBtu on September 17 and the national spot average at $2.640/MMBtu for September 18 flows. Record U.S. dry gas production — averaging over 110 Bcf/d year-to-date on the back of a Permian drilling surge that pushed the total rig count to a 17-month high of 625 — continues to weigh on prices.
Some support comes from five consecutive weeks of below-average storage builds, and analysts expect the upcoming start of annual maintenance at the Cove Point LNG terminal in Maryland to temporarily ease export demand, potentially allowing injections to pick up pace into early October.
Storage Report: The EIA reported a 44 Bcf injection for the week ended September 11 — 5 Bcf below market expectations and the fifth consecutive below-average build. Total working gas stands at 3.298 Tcf, roughly 118 Bcf (4%) above the five-year average and 122 Bcf below year-ago levels. Another below-average build is projected for the week ended September 18.
Weather: NOAA’s 6–10 day outlook (valid September 23–27) shows above-normal temperatures across most of the country, with the highest probabilities along the southeast Texas Coast and Northern High Plains. The Northeast and northern Mid-Atlantic are the exception, trending near-to-below-normal — a bearish signal for demand as the market moves into the fall shoulder season.
Make Your Choice Gas Selection in Three Easy Steps
Click here to access our online tool, or call our Choice gas commodity experts at 1 (877) 790-4990.
Step 1: Enter your account number
- Your Black Hills Energy account number is located at the top right-hand corner of your bill.
Step 2: Review price options and make your selection
Step 3: Confirm your selection and enter your control number
- You received a control number in your 2026 Choice Gas selection packet mailed to you from Black Hills Energy. If you cannot locate this, you can retrieve your control number by calling 877-245-3506 or visit choicegas.com
Once enrolled, you will be removed from supplier marketing communications within 24 hours.


Sign Up for Our Energy Newsletters
Sign UpRecent Posts